
Kikoff - Build Credit Quickly
- Rating
- 4.8
- 17K Reviews
- Downloads
- 5M+
- Age Rating
- Everyone
App Specs
- Version
- 1.181.3223
- Updated
- Requires
- 7.0
- Price
- Free
Screenshots
Our Review
 Analysis byMileapps
When I look at a credit-building app, I want to know what I’ll actually do with it on an ordinary day—not just whether it promises progress. Kikoff - Build Credit Quickly is a free finance app from Kikoff Inc. that approaches credit-building through a dedicated account rather than a conventional credit card. Its central appeal is that getting started does not require a credit check, which may make it worth considering if you’re trying to establish credit and want to avoid applying for another standard card.
I’d think of Kikoff as a structured routine, not a quick fix. You still need to understand the account, keep track of any activity and payments, and give credit-building habits time to work. That makes it a better fit for someone who wants a manageable first step than for someone expecting an immediate score change or a replacement for everyday spending tools.
From sign-up to a credit-building routine
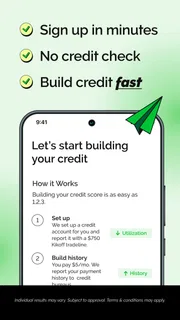
Jumping into Kikoff is surprisingly smooth. The app is available for both Android and iOS, so no one’s left out. Once you download it, setting up an account is a breeze. You’ll just need to provide some basic info, and you’re off to the races. One thing that caught my eye right away is how the app doesn’t require a hard credit check to get started. This is huge because, as you might know, hard checks can ding your score.
That no-check starting point is useful, but I wouldn’t treat it as a promise that every person will see the same outcome. A credit profile depends on more than opening one account, and the practical benefit comes from using the product consistently and paying attention to its terms. Before signing up, I’d make sure I understand what the account involves and how I’ll remember to manage it alongside rent, utilities, and other monthly obligations.
The account and the first steps
Now, let’s talk about the star of the show: the Kikoff Credit Account. This is where things get interesting. Essentially, Kikoff gives you a $500 revolving line of credit. You might think, "What’s the catch?" but honestly, there isn’t much of one. The app encourages you to make small monthly purchases ($5 a month) in their store, which you then pay off. It’s like a practice run for handling credit responsibly.
That setup is quite different from applying for a regular credit card and using it for groceries or fuel. The activity is tied to Kikoff’s own store, so I’d approach it as a focused credit habit rather than a source of flexible spending. A useful first step is to decide in advance what you’ll buy and how you’ll handle the payment, instead of treating the available line as money you can casually spend.
For example, imagine you’re reviewing your finances on payday and want to build a small, repeatable task into the month. You could check the account, make a planned purchase, and note the payment due date in the same calendar you use for other bills. That workflow keeps credit activity separate from the money you need for essentials. It also makes the routine easier to audit later: you can see what you did, what you owe, and whether anything needs attention.
What the reporting can and can’t do
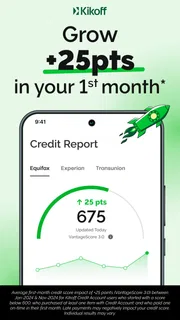
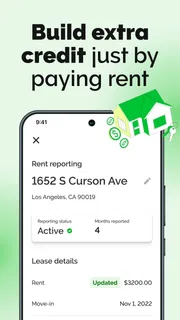
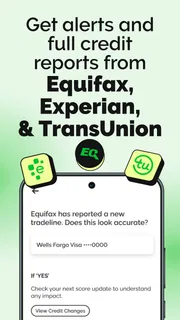
The beauty here is that these transactions are reported to major credit bureaus. So, each time you make a purchase and pay it off, it gives your credit score a little nudge. The app’s design makes it super simple to track your progress, and seeing those positive reports flow in is pretty satisfying.
I’d keep expectations measured. Reporting account activity can contribute to a credit history, but it doesn’t guarantee a particular score increase or a specific timetable. Your broader record matters too, and a missed payment elsewhere can undermine the progress you’re trying to make here. I’d use the app as one piece of a larger plan: stay current on existing obligations, check your credit reports through appropriate channels, and avoid taking on spending just to create activity.
There’s also a useful distinction between seeing activity inside an app and seeing how it appears in a credit file. Those are related, but not interchangeable. If you’re using Kikoff because you’re preparing for a future loan or rental application, leave room for reporting and review rather than waiting until the last minute. Building a track record is a gradual process, so I wouldn’t sign up right before an application and assume the account will change the result.
Keeping the routine manageable
I’ve got to give a shout-out to the design team because the app’s interface is sleek and intuitive. Everything is laid out in a way that just makes sense. There’s no clutter, no unnecessary distractions, just a straightforward path to better credit. The dashboard gives you a clear view of your credit line, purchase history, and upcoming payments. It’s all about keeping you informed and empowered.
In practice, I’d use that overview as a check-in rather than something to monitor constantly. A quick review after making a purchase can help you confirm the activity appears as expected; another glance before the payment is due helps keep the account from becoming one more forgotten bill. If you already use a budgeting app or calendar, adding the payment reminder there can be more reliable than depending on memory or switching between screens.
This is one place where the product’s simplicity has a trade-off. A dedicated account can make a small credit routine feel approachable, but it doesn’t replace a full budget, a complete credit-report review, or a spending account for daily purchases. If you’re juggling several due dates, the real value will depend on whether you build Kikoff into the system you already use instead of treating it as a separate task you might forget.
Learning while you use it
One feature I genuinely appreciate is Kikoff’s focus on education. The app doesn’t just throw numbers at you; it helps you understand what they mean. There’s a whole section dedicated to financial literacy, filled with tips and tricks on improving your credit health. Whether you’re a credit newbie or a seasoned pro, there’s something here for everyone.
I’d get the most from that material by connecting it to a real decision. If a lesson discusses payment history, for instance, use it as a reason to review your due-date routine; if it covers credit use, think about how a dedicated account differs from carrying balances on a card. The practical payoff is not simply reading tips, but turning one of them into a habit you can keep after the novelty of a new app wears off.
For someone new to credit, this learning angle can make the process less intimidating. For someone who already understands credit basics, the educational content may feel less essential, and the account itself will matter more. Either way, I wouldn’t confuse general guidance with personal financial advice: if you’re making a major borrowing decision, compare the terms and consequences of all your options rather than relying on an in-app lesson alone.
Where Kikoff fits among credit options
Compared with a secured credit card, Kikoff offers a different kind of starting point. A secured card generally involves using a deposit and can be used for ordinary card purchases, while Kikoff’s described approach centers on purchases in its own store. That distinction matters: if your main goal is to build a record while also having a card for everyday spending, a secured card may be more useful, provided you’re comfortable with its application and deposit requirements.
A credit-builder loan is another common alternative, but it works differently from revolving credit and may involve a scheduled loan-payment structure. I’d compare the commitment, payment timing, and total cost before choosing between products. Kikoff’s appeal is the contained, app-based routine; the trade-off is that it is not a universal substitute for a card or loan, and the right choice depends on what kind of credit history you need and what you can reliably manage.
It may also be a poor fit if you already have several accounts and are looking for a broad financial dashboard, rewards, or a way to finance regular purchases. In that situation, adding another account could create more administration without solving your actual problem. I’d choose Kikoff when the goal is specifically a simple credit-building routine, not when I need borrowing flexibility or a comprehensive money-management tool.
Costs, safety, and the fine print
Security is a biggie for any financial app, and Kikoff doesn’t skimp here. The app uses bank-level encryption to protect your personal info, so you can breathe easy knowing your data is safe. I also love how transparent they are about fees—or rather, the lack of them. No hidden charges, no annual fees, just a straightforward $5 monthly purchase that you control. It’s a refreshing change from the usual credit card fine print.
I’d still read the current account terms before committing, especially because a product’s payment obligations matter more than a reassuringly simple routine. Keep an eye on the purchase and payment details shown in your account, and make sure the transaction fits your budget. “Small” is relative: even a modest recurring obligation is worth planning for if your income varies or you’re already balancing other bills.
On the privacy side, encryption is a helpful safeguard, but it isn’t a reason to skip ordinary caution. Use a device you trust, protect your sign-in details, and review account activity when you check your finances. I’d also avoid sharing sensitive account information in messages or screenshots. Those are sensible habits for any finance app, particularly one you’re using to manage personal credit information.
Who will get the most out of it
Kikoff is most appealing to people who want a first, fairly contained credit-building step and are comfortable handling a small account routine from a phone. It may suit someone with a limited credit history who wants to avoid a hard credit check to get started, or someone who finds traditional card applications stressful and would rather begin with a more focused product.
It is less compelling for someone who already has a strong credit profile, needs a card for normal purchases, or wants to borrow money. It’s also not a shortcut for anyone who cannot reliably keep track of payments. If your finances are currently unstable, I’d prioritize essential bills and a workable budget before adding any recurring account activity. The best credit-building tool is one you can manage without forcing you to spend money you need elsewhere.
On Android, the app is listed for Everyone and requires Android 7.0 or later. It is free to download, and its current version is 1.158.2511. The app was released on March 25, 2021; its average rating is 4.8 from around 115,000 ratings, with roughly 15,000 written reviews and over one million installs. Those figures suggest many people have tried it, but they don’t tell me whether the account suits your circumstances, so I’d still judge it by the workflow and terms.
One question people often have is whether they need to make a large purchase to make the account worthwhile. I wouldn’t assume that bigger spending is better; the sensible approach is to follow the account’s terms and keep any activity within an amount you can comfortably repay. Another is whether the app can guarantee a score improvement. No app can make that outcome certain, so I’d treat reported activity as a way to build a record, not a promise of a particular result.
If you’re deciding between Kikoff and a conventional credit card, ask yourself whether you need everyday purchasing power or mainly want a more contained credit routine. If you need the former, compare card options and their terms. If you mainly want the latter and are willing to manage a dedicated account, Kikoff may be worth exploring. And if you’re already using another credit-builder product, compare how each one fits your budget before opening an additional account; more activity is not automatically better.
And there you have it, folks. If you’re serious about building your credit but don’t want the hassle of traditional credit cards, Kikoff - Build Credit Quickly might just be your new best friend. It’s simple, effective, and designed with the user in mind. So, next time you’re lounging on the couch with your phone in hand, give Kikoff a try. You might just find it’s exactly what you’ve been looking for.
Pros and Cons
Pros
- User-friendly interface for easy navigation.
- No interest or fees on credit lines.
- Reports to major credit bureaus regularly.
- Helps build credit history efficiently.
- Secure and private data handling.
Cons
- Limited features compared to competitors.
- Requires a subscription for full benefits.
- No mobile payments integration yet.
- Customer support can be slow to respond.
- Limited educational resources available.
Frequently Asked Questions
What is Kikoff and how does it work?
Kikoff is a financial app designed to help users build their credit quickly and efficiently. By offering a credit line that reports to major credit bureaus, Kikoff enables users to make small purchases and repay them over time, establishing a positive payment history. It’s a simple way to improve your credit score without incurring high fees or interest rates.
Is Kikoff safe to use for building credit?
Yes, Kikoff is safe to use. It employs bank-level encryption to protect your personal and financial information. Additionally, Kikoff only reports your payment activity to the credit bureaus, ensuring that your data is not shared with unauthorized parties. Users can confidently use the app to build credit without compromising their security.
How quickly can I expect to see improvements in my credit score with Kikoff?
Improvements in your credit score can vary depending on individual circumstances. However, many users report seeing positive changes within a few months of consistent use. By consistently making on-time payments and keeping your credit utilization low, you’re likely to see a gradual increase in your credit score as Kikoff reports your activity to the credit bureaus.
Does Kikoff have any fees or hidden charges?
Kikoff prides itself on being an affordable solution for credit building. There are no hidden fees or high-interest rates. Users pay a small monthly fee for the service, and there are no additional costs for using the credit line, making it a transparent and budget-friendly option for improving your credit score.
Can Kikoff be used alongside other credit-building strategies?
Absolutely, Kikoff can be used in conjunction with other credit-building strategies. Whether you’re using secured credit cards, becoming an authorized user, or maintaining low balances on existing credit lines, Kikoff complements these methods by offering another avenue to demonstrate responsible credit use and improve your score over time.

Download Kikoff - Build Credit Quickly
Close Matches in This Category
 Google WalletFinance4.4
 Airtel: Recharge, Bank & LoansFinance4.0
 DANA Indonesia Digital WalletFinance4.5
 Binance: Buy Bitcoin & CryptoFinance4.8
 Inter Banking & Money TransferFinance4.4
 Cash AppFinance4.7
 PayPal - Pay, Send, SaveFinance4.2
 MetaTrader 5 — Forex, StocksFinance4.7